Modine has two routes to renewed investor interest. Its cooling business is expanding with data-center demand, and reported acquisition discussions have added a potential corporate catalyst. Selected for this research series because of identified growth potential, MOD offers a way to study the infrastructure behind AI computing ahead of its November 18 Investor Day.
Key takeaways
- Data-center cooling gives the growth thesis an operating foundation.
- Reported Samsung discussions introduce an additional, unconfirmed catalyst.
- Investor Day offers a near-term checkpoint for margins, investment and cash conversion.
Cooling capacity is becoming a strategic asset
Computing expansion requires equipment that removes heat reliably. Modine supplies thermal-management products that help customers operate increasingly power-intensive facilities. The commercial opportunity grows when customers need more cooling capacity per installation, creating a route to larger orders even before counting additional buildings.
That gives the company an identifiable growth mechanism. An equipment supplier can benefit from both the quantity of facilities and the complexity of each project. Investors should therefore follow product mix, production capacity and delivery performance alongside headline sales. Winning an order creates work, while successful installation and collection create economic value.
On November 13, Bloomberg reported that Samsung was in talks to acquire Modine. The report adds a possible strategic premium to the cooling business. Its status remains reported discussions, with a definitive agreement and transaction price still unannounced in the evidence reviewed. Treating a deal as completed would overstate the information available. Reported acquisition discussions
The investment case can still be evaluated through Modine’s own operations. Its November 3 results reported fiscal second-quarter sales of $994.4 million, up 35%, with data-center growth of 95%. Adjusted EPS reached $1.35, compared with GAAP diluted EPS of $0.56. The distinction matters when assessing recurring operations and transaction-related effects. Modine quarterly results
Growth needs to convert into cash
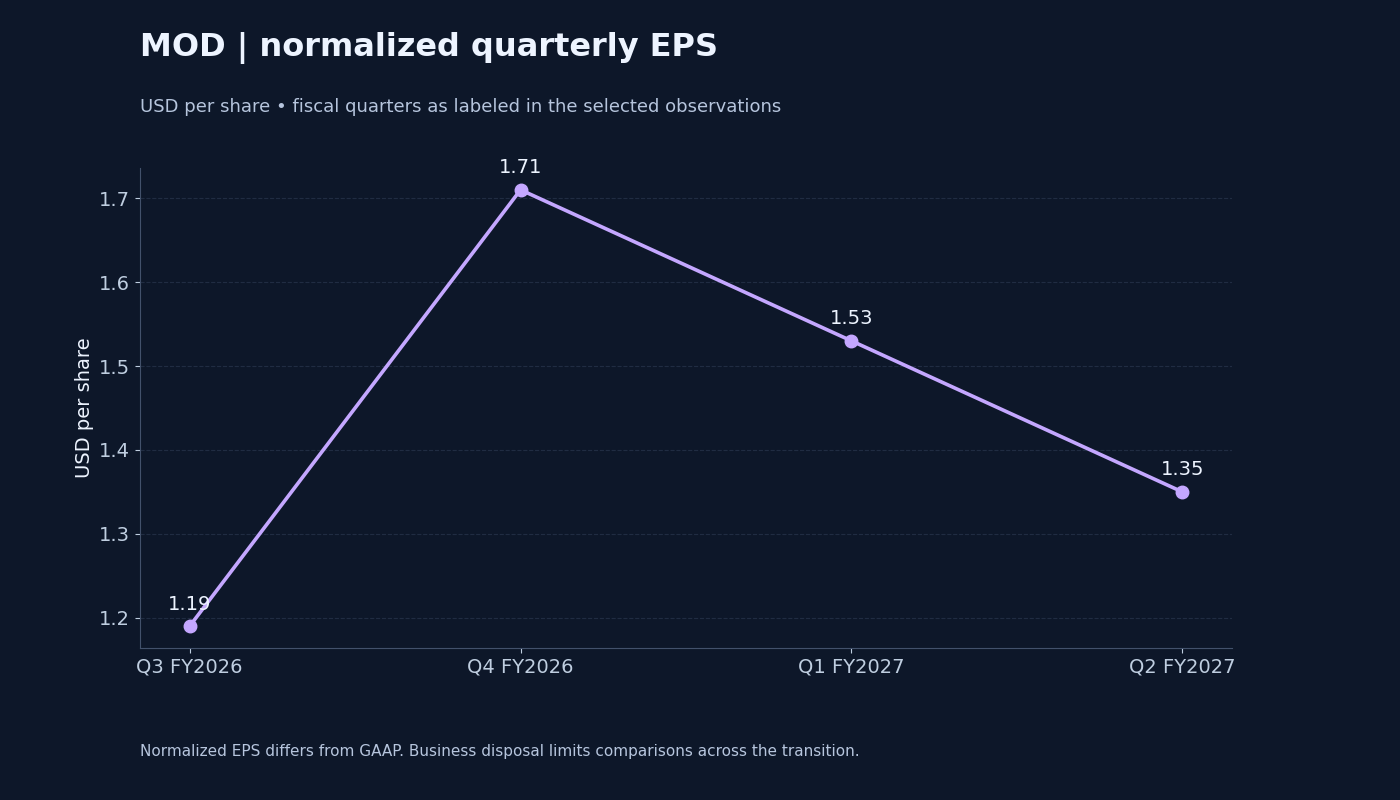
The normalized EPS chart shows $1.19, $1.71, $1.53 and $1.35 across the selected fiscal quarters. It gives a compact view of earnings capacity, while the change in business perimeter requires care with comparisons. Modine completed the Performance Technologies separation on October 1, making the continuing thermal-management business the more relevant forward reference.
The release set continuing-business fiscal 2027 revenue guidance at $3.1–$3.2 billion and adjusted EBITDA guidance at $470–$500 million. Gross margin in the reported quarter was 20.7%, down 160 basis points. First-half free cash flow was negative $145.6 million. Those figures connect the attractive sales opportunity with the capital needed to deliver it. Continuing-business outlook and cash flow
For a growing manufacturer, capacity spending can precede revenue and cash receipts. The constructive scenario is that this spending supports successful deliveries and subsequently improves cash generation. The weaker scenario involves further working-capital demands, delayed commissioning or margin pressure. The next report needs to show which path is developing.
The latest price and the completed-session setup
The latest exchange quote was $136.00, +28.18%, at Nov 13, 2026 10:52 AM ET. This is an intraday reading from November 13. The compatible 52-week trading range was $87.84–$323.25, placing that quote 20.5% of the way from the low to the high.
The latest completed-session close, on November 12, was $106.10, with a -0.53% daily return and +16.10% five-session return. Its 50-session average was $160.43, with price -33.86% relative to that average. The chart uses those completed closes. Annual-range position measures where a price sits between its extremes, while the weekly return measures change over time.
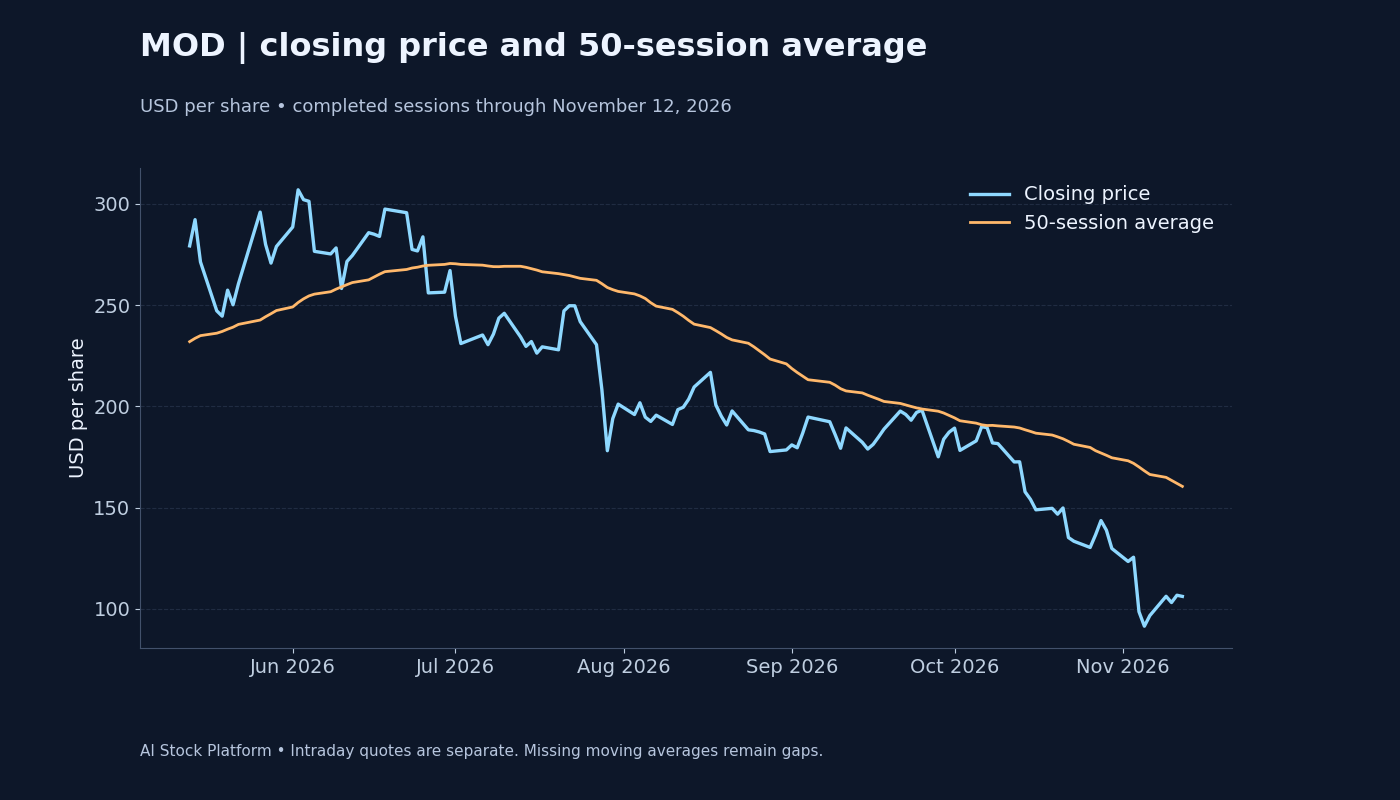
Friday’s advance brings the shares materially closer to the moving average. That is a meaningful improvement in price behavior, although the completed-session indicators still describe the earlier, weaker setup. The recovery becomes more persuasive if follow-through holds beyond the initial transaction headlines.
Reading the three research signals
The November 12 Price Score was 4.76/5, changing -0.12 points from November 11. Momentum V3 was 47.92/100, changing -0.06 points. The AI Score history for November 12 recorded 2.24/5.
Price Score currently combines weekly-return points, inverse distance from the 50-session average, industry sentiment, inverse annual-range position and rank movement. Its recovery-oriented design can favor a beaten-down share. Momentum describes price-feature strength, while AI Score adds a separate model view. Their different purposes explain why a constructive company catalyst can arrive alongside mixed historical signals. Friday’s live movement will enter subsequent completed-session measurements. Score methodology
Useful comparisons in thermal infrastructure
Vertiv provides a focused comparison for data-center power and thermal infrastructure. Trane Technologies offers a broader HVAC reference with a different business mix. Their platform pages help compare price behavior and financial delivery across related equipment markets. Modine’s disposal and takeover headlines make simple valuation comparisons particularly sensitive to accounting dates. Vertiv Trane Technologies
The most useful comparison concerns delivery quality. Growing orders are more valuable when suppliers preserve margins, avoid costly production bottlenecks and collect cash. A business that scales successfully can support earnings revisions, while an equally fast-growing supplier with weaker execution may require more financing to maintain the same sales trajectory.
The next checkpoint is November 18
Modine’s scheduled Investor Day on November 18 gives management an opportunity to explain the continuing business, investment requirements and growth priorities. It could strengthen the thesis through clearer evidence of delivery capacity and cash conversion. Any commentary on strategic discussions would also be material, although an event date creates no certainty that a transaction update will arrive. Investor events
For the coming weeks, the constructive case combines strong customer demand with a better share-price trend. The main inhibitors are execution costs, weaker margins and the possibility that reported acquisition discussions end without an agreement. A sustained operating improvement would give the company’s recovery a foundation extending beyond one day’s rally.